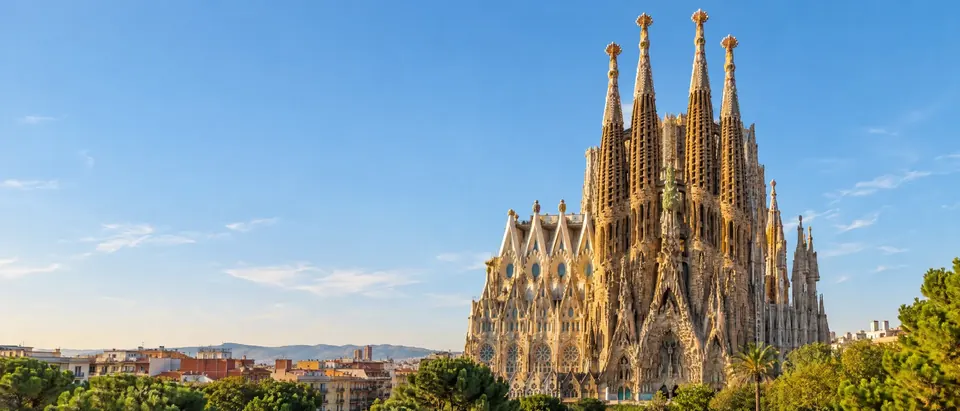
The Sagrada Família in Barcelona
AI-generated image
Visit the full Hipoteken website
Euribor 12M
This month, avg
3.216%
October 2026, 1–14 Oct average
Official monthly
3.247%
September 2026

Updated 15 October 2026

Barcelona

Buying here?
We handle the mortgage.

Barcelona mortgages for international buyers

We arrange mortgages across Barcelona and its coast — the city itself, Sitges and the Garraf, the Maresme, Sant Cugat del Valles, Castelldefels, Badalona and the Costa Brava — for buyers from the UK, Ireland, the Netherlands, Germany, Scandinavia, the USA and beyond. Every step is handled remotely, so you never need to fly out to sign a form.

  • Rental demand outstrips supply across the city
  • We put banks in competition for you
  • Increase your chances of a mortgage!
  • Same day appointments available
  • Access preferential rates
  • Reduce the stress and let us work for you

Instant Simulation!

It takes 1 minute to learn how much you can borrow and monthly payment!

Please enter the property price.

Non-resident: you pay income tax outside Spain. Resident: you pay income tax in Spain.

Please enter an age between 18 and 74.
Excellent Read our reviews → 4.9/5 140 reviewson Trustpilot

Registered and regulated by the Bank of Spain. Registration number D647 — HIPOTEKEN, S.L. See more here

Where the licence matters as much as the rate

Rent in Barcelona is very high because demand outstrips supply, which makes the investment case obvious and the rules complicated. Buy-to-let restrictions and frozen rental licence zones mean a case built on short lets needs checking before you offer, not after. Lenders here are experienced and quick; the licensing is what slows things down.

Maximum advance and term depend on your residency, age and income, and vary between lenders. We confirm the exact figures for your purchase before you commit to anything.

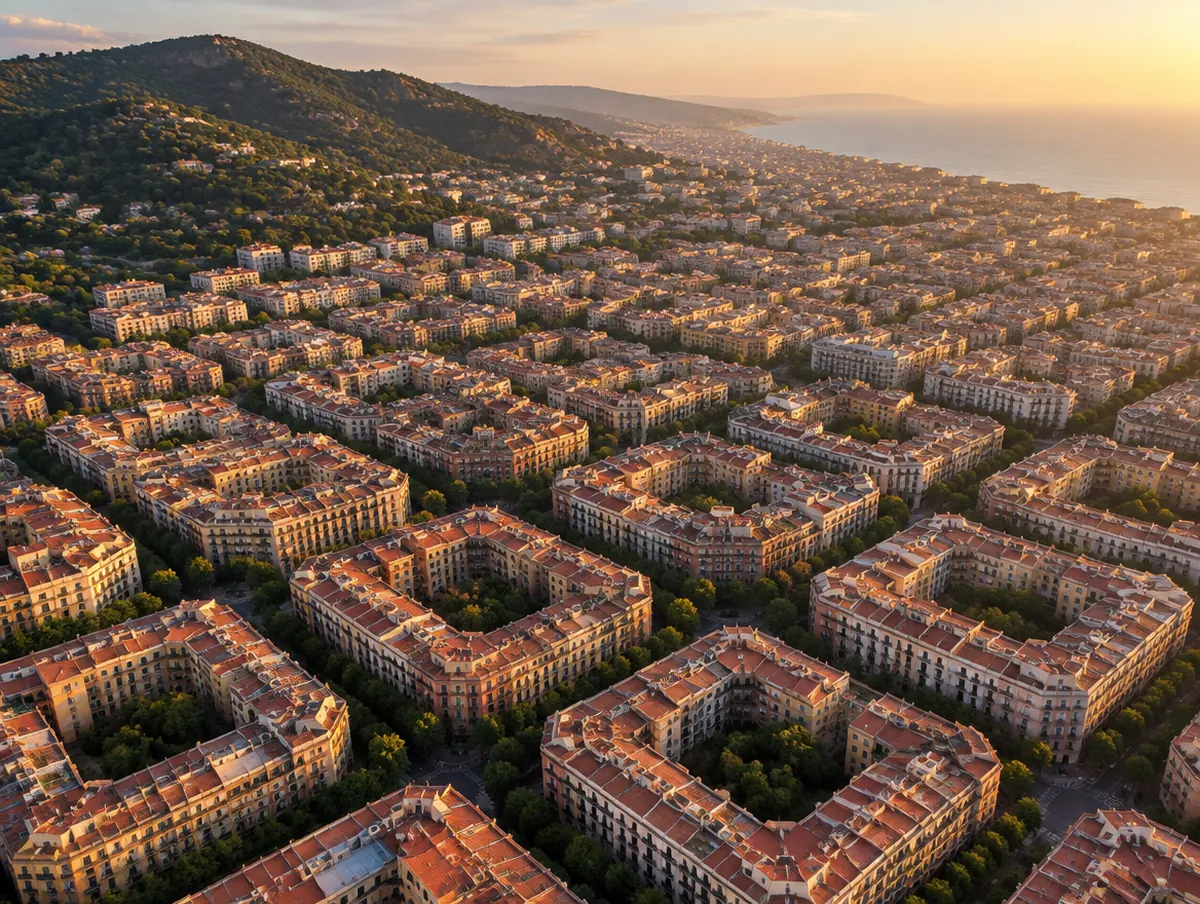
AI-generated image: an elevated view over a dense city of regular square blocks with inner courtyards and tiled rooftops, wooded hills on one side and sea haze on the other, late afternoon light, no people AI-generated

A city first, a coast second

Barcelona works as a city first and a coast second. An airport 17 kilometres out handling forty million passengers a year, three kilometres of city-centre beach created for the 1992 Olympics, and rail lines that make living well to the north entirely practical. Rent is very high because demand outstrips supply, and the licensing that follows from that shapes what a lender will fund.

AI-generated image: an aerial view down a straight grid avenue showing chamfered corner blocks and tiled rooftops in low golden light, no people visibleAI-generated

Four city neighbourhoods

Barcelona city

Eixample's grid of modernista apartments, El Born's narrow streets behind the old port, Gracia's squares and La Barceloneta's beachfront blocks: four distinct markets inside one city. Rental demand is relentless and supply is not, but buy-to-let restrictions and frozen rental licence zones mean an investment case built on short lets has to be checked first. Lenders here are experienced and quick; the licence question is what slows a purchase down.

EixampleEl BornEl GraciaLa Barceloneta
AI-generated image: a whitewashed seafront church on a rocky promontory above a curved sandy bay at first light, palm trees along the promenade, no peopleAI-generated

Coast south of town

Sitges and the Garraf

One of Catalonia's most attractive coastal towns, a short run down the coast on the rail line, with a long-established international community. Sant Pere de Ribes sits just inland with more house for the money and Vilanova i la Geltru anchors the southern end. Values are high but transactions are frequent, so comparables exist and valuers are confident, which is what keeps a mortgage on schedule.

SitgesSant Pere De RibesVilanova I La Geltru
AI-generated image: terraced vineyards and villas on a green hillside dropping towards the mediterranean, a rail line and a narrow beach below, clear morning lightAI-generated

Rail coast to the north

The Maresme

North of the city, hillside towns looking back at the sea with good rail connections into Barcelona, which makes this a practical base for anyone working in the city but wanting to live by the water. Mataro is the working capital; Alella, Cabrils and Sant Andreu de Llavaneres are where the villas sit. Established stock and steady turnover mean lenders know the line well.

MataroAlellaSant Andreu De LlavaneresSant Vicenc De MontaltCabrilsCabrera De MarArgentonaVilassar De Dalt
AI-generated image: a leafy modern residential street of low apartment buildings with a romanesque monastery tower rising behind, wooded hills on the skylineAI-generated

Inland Valles and schools

Sant Cugat del Valles and the inland Valles

Through the Collserola tunnel and into a slightly different climate: international schools, a young professional population and the technology employers that follow them. The apartment and townhouse stock is modern and consistent, which valuers like, and demand from salaried local buyers keeps the market liquid. If your mortgage rests on employment income rather than rental projections, this is comfortable ground.

Sant Cugat Del VallesL'Ametlla Del VallesSant Just DesvernEsplugues De Llobregat
AI-generated image: a wide flat sandy beach stretching to a hazy headland at dawn, low dunes and pine woodland behind, calm sea, entirely emptyAI-generated

Beach beside the airport

Castelldefels and Gava

A long flat beach close to the airport with the Garraf hills behind, popular with international staff on fixed-term contracts. That makes rental demand reliable and the housing stock familiar, which is a combination lenders price without hesitation.

CastelldefelsGava
AI-generated image: a working seafront of mid-century apartment blocks behind a wide beach and a lone brick chimney, flat grey-blue sea, soft overcast lightAI-generated

Northern city extension

Badalona

The city's northern continuation, on the metro and noticeably cheaper than the districts across the Besos. Entry prices are low and the stock is straightforward apartments that value easily, though building age is the thing a survey tends to catch here.

BadalonaTeiaPremia De Dalt
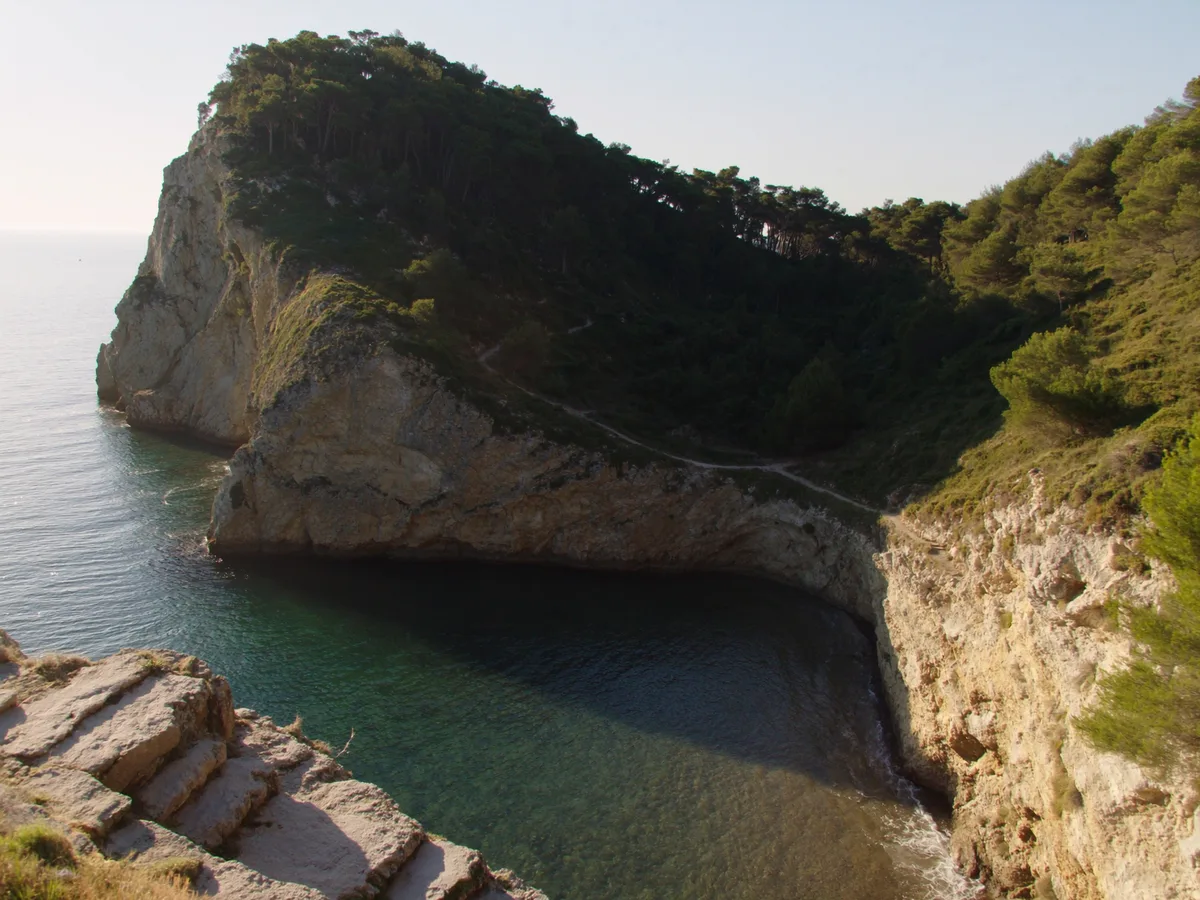
AI-generated image: pine-topped cliffs above a narrow rocky cove with clear green water and a coastal footpath cut into the rock, late afternoon light, no peopleAI-generated

Girona's rugged coast

The Costa Brava

The Wild Coast up in Girona: rugged cliffs, forested capes and hidden coves, with Begur and Platja d'Aro at the expensive end and Blanes and Roses at the accessible one. Seasonal and second-home led, so lenders look harder at how the purchase will be serviced out of season.

BegurPlatja D'aroRosesBlanesTossa De MarPalamosSant Feliu De GuixolsL'Escala

Buying somewhere not on this list?

A rural finca, a plot for a self-build, a village nobody mentions in the brochures — we arrange mortgages right across the archipelago. Send us the address and we will tell you which lenders will look at it, usually the same day.

Ask about your property

Let’s get started!

Six steps from first conversation to keys in hand. We handle the parts that are slow, confusing or in Spanish.

  1. Discovery

    Tell us about your situation — property price, area of interest, your tax residency and your income. The best way to do this is to schedule a call or send us your details. You will come out of this call with a full understanding of the possibilities and of the process ahead.

  2. Simulation & start!

    As a follow-up to the call you receive a detailed simulation of your potential mortgage — savings needed, monthly repayment, costs. We also set out exactly which documents are needed to get going.

  3. Let’s document!

    This is the part where we need you. The more complete your file, the better your chances of a fast and competitive mortgage offer.

  4. Application & Negotiation

    We work through your documents and apply to get banks competing for your mortgage, fighting on your behalf for the best rates and terms.

  5. Valuation of the property

    An official appraisal is coordinated between your estate agent or vendor and a licensed valuation company.

  6. Completion

    Once everything is tied up, our specialised completions team supports you all the way. We coordinate with your estate agent, solicitors, bank and notary to push the process through smoothly.

Meet the team

Our team is based in Valencia, Spain, working with mortgages all around Spain.

Raj Kumar Sirwani, CEO and Founder at Hipoteken
Raj Kumar Sirwani
CEO & Founder
SpanishEnglish
Philip Lee, Director at Hipoteken
Philip Lee
Director
SpanishEnglish
Daniel Morante, Mortgage Adviser at Hipoteken
Daniel Morante
Mortgage Adviser
SpanishEnglish
Alberto García, Mortgage Adviser at Hipoteken
Alberto García
Mortgage Adviser
SpanishEnglishGerman
Alejandro Madrigal, Mortgage Adviser at Hipoteken
Alejandro Madrigal
Mortgage Adviser
SpanishEnglish
Nuria Garca, Mortgage Adviser at Hipoteken
Nuria García
Mortgage Adviser
SpanishEnglish
Louisa Koole, Mortgage Adviser at Hipoteken
Louisa Koole
Mortgage Adviser
SpanishEnglishDutch
Luis Boris Grateron, Completion Coordinator at Hipoteken
Luis Boris Grateron
Completion Coordinator
SpanishEnglishGerman
Daniel Santiago, Business Development at Hipoteken
Daniel Santiago
Business Development
SpanishEnglish
Maria Jos Valero, Completion Coordinator at Hipoteken
Maria José Valero
Completion Coordinator
SpanishEnglish

Meet the whole team on hipoteken.com →

This is where we focus and specialize

Most of our Barcelona clients live outside Spain and are buying here for the first time. Some already live in Spain. We handle both.

Non-resident buyers

You live and pay tax outside Spain. Expect to borrow up to around 70% of the property price and fund the rest plus costs yourself. This is our largest group by far.

Spanish residents

You live and pay tax in Spain. Loan-to-value typically rises to 80%, and a wider set of lenders opens up to you.

Investment purchases

Buy-to-let and second homes. Lenders assess these differently, and the right bank matters more than the headline rate.

Remortgaging in Spain

Already have a Spanish mortgage on a worse rate? Moving lender is often straightforward and the saving over a full term can be substantial.

Construction & renovation

Building or substantially renovating needs a different product and a lender comfortable with staged drawdown.

Complex income

Self-employed, company director, multi-currency or several income sources. This is where a broker earns their keep.

★★★★★
Raj was efficient and professional from start to finish, from quickly finding the best offer through to the closing process.
Google review Jonathan & VictoriaUnited Kingdom
★★★★★
We approached other brokers and banks directly and could not get the offer we wanted. Raj and the team secured us the best deal.
Google review DanielUnited Kingdom
★★★★★
Our situation was a bit tricky and Raj managed all the questions from the bank with ease. He secured us a great deal.
Google review MelissaUnited States
★★★★★
I had a more difficult application as a self-employed person. With unbridled energy he applied to various banks and got it.
Google review KarinNetherlands
★★★★★
Not being aware of the way of banking in Spain, we can fully recommend Hipoteken. Good and fast communication.
Google review ArminGermany
★★★★★
Hipoteken have been a God send, not least because I am self employed in the UK and had difficulty proving my income.
Google review SamUnited Kingdom
★★★★★
Simply without Hipoteken I could not have purchased my new property. They supported me throughout the entire process.
Google review AlessandroItaly

Reviews published on Trustpilot and Google.

Book a call with a mortgage adviser

Pick a time that suits you. Twenty-five minutes, by phone or Google Meet, with an adviser who works on international cases every day. No cost and no obligation.

Initial mortgage consultation 25 minutes · by phone or Google Meet · English, Spanish, German or Dutch
Free

Not loading? Open the booking page in a new tab Prefer to write instead? Send us your details and we will come back to you.

Frequently asked questions

The questions buyers ask us most often about mortgages in Barcelona, answered directly.

Can I get a mortgage in Barcelona as a non-resident, or if I have just moved to Spain?

Yes — clearly. Spanish banks lend both to non-residents and to international clients who have only recently moved to Spain, as long as you meet their lending requirements.

What are the key factors Spanish banks look at to approve a mortgage?

Criteria vary from bank to bank, and even within the same bank depending on the route your application takes to reach them. The key factors are:

  • Debt-to-income ratio (DTI) — the central ratio a bank uses to assess a mortgage. Each bank has its own criteria and its own way of calculating it, but as a general rule they will lend where DTI stays below 35%.
  • Stability of income — how long you have been in your current job, or running your current business, matters a great deal.
  • Saving capacity — banks want to see clients who save and who run their finances in an organised way. Having the funds available to cover the share the bank does not lend is essential.
  • Credit history — they pay less attention to the score itself than to your record of past borrowing, and to any defaults or late payments.
How much can I borrow for a property in Barcelona?

Spanish banks set a maximum loan-to-value (LTV) based on the currency you are paid in and on your tax residency.

As a general rule, non-resident mortgages are limited to 70%, while residents in Spain can generally borrow up to 80%. Some exceptions apply, and across the market the full range runs from 50% to 75% for non-residents.

That is the maximum, though. Your finances still have to show the bank what it wants to see on DTI, on savings and on the rest.

How much deposit do I need to buy in Barcelona?

On a non-resident mortgage where the bank covers 70%, you would need to cover the remaining 30%, plus the costs of buying. Those costs vary considerably depending on the region of purchase, and can range from 8% to 15%.

What are the costs of buying a property in Barcelona?

Beyond the property price itself, you need to budget for the following:

  • Taxes
    • Resale: between 6% and 11%, depending on the region of purchase and the price of the property.
    • New build: 10% VAT, plus stamp duty — which again varies by region, between 0.5% and 1.5%.
  • Legal costs — we recommend appointing a lawyer to carry out the legal checks and to guide you through the whole purchase process. Allow around 1%, although the percentage will be higher on lower-value properties.
  • Notary and land registry costs — allow up to 1%.
And what are the costs of obtaining a mortgage in Spain?

By law, Spanish banks cover all of the set-up costs of a mortgage. That leaves the borrower with two: the valuation of the property — between €500 and €2,500, depending on its value — and the broker's fee.

Our fee depends on the mortgage amount. Once we have spoken and understood your situation, we prepare a personal simulation for you, and the fee is set out in full there — so you see it alongside the mortgage figures, before you commit to anything. It is purely success-based: nothing is payable until the purchase completes.

How long does it take to get a mortgage in Barcelona?

Once we have collected all of your financial documents, we apply to the banks for approval. That can take anywhere from 48 hours in straightforward cases to a few weeks in more complex ones.

Bear in mind, too, that banks slow down substantially over holiday periods — summer, Easter, Christmas and local holidays.

Once your mortgage is approved, carrying out the property valuation and getting everything ready to sign takes a further four to six weeks.

How do mortgage rates work in Spain?

Unlike many countries, Spain offers fixed rates that run for the entire life of the mortgage. So when you sign, you can fix your interest rate for the whole term.

The types of mortgage available are:

  • Fixed rate — one interest rate for the whole term.
  • Variable rate — generally indexed to 12-month Euribor. The rate is recalculated every 6 or 12 months, and is the index rate plus an agreed spread.
  • Mixed rate — a combination of the two. The rate is fixed for typically 5 to 10 years, after which the mortgage becomes variable: indexed, and revised every 6 or 12 months.

Rates move a great deal with central bank rates and with Euribor, so the best way to find out where they stand today is to speak to us.

Do I need an NIE to get a mortgage in Barcelona?

Yes, you will need an NIE number eventually — but we can start the process without one, and we will guide you through the easiest way to obtain it later on.

Can the mortgage process be done online?

Yes. With us, the entire process is handled online, with no need to travel or to visit banks until the last stages. We work with banks that are able to run the process fully online.

Signing the purchase and the mortgage at the notary is the only step that requires travelling — and even then, it is very common to give power of attorney to your lawyer so that they can sign the deeds on your behalf.

Why use a mortgage broker rather than going straight to the banks?

Experience in mortgages allows a broker to present your application in the best possible way, to the right banks, and then to push those banks for approval and for the best terms available.

With mortgage terms typically running 15 to 25 years, a small reduction in the interest rate obtained can mean thousands of euros saved over the life of the loan.

And that is before the hassle of shopping around bank after bank yourself — waiting on answers that never arrive, or getting a flat no simply because something in your file was not understood.

We do the hard work of understanding your case, presenting it to the banks most likely to say yes, and fighting for the best possible terms for you.

Free & no obligation initial consultation Fees only on success

Contact us

Send us your details, along with anything specific you would like us to know, and we will be in touch shortly. Remember:

  • No obligation and no cost to enquire
  • A real adviser, not an automated quote
  • We work in English, Spanish, German and Dutch
  • Your details are never sold or shared

Your details (obligatory fields)

Please enter your first name.
Please enter your last name.
Please enter a valid email address.
Please enter your phone number.
Please accept the privacy policy to continue.

Hipoteken is an independent mortgage intermediary. This is an enquiry, not a mortgage application, and places you under no obligation.

Ready to find out what you can borrow? No obligation, no cost, and no fee until your mortgage is approved.

Contact us WhatsApp