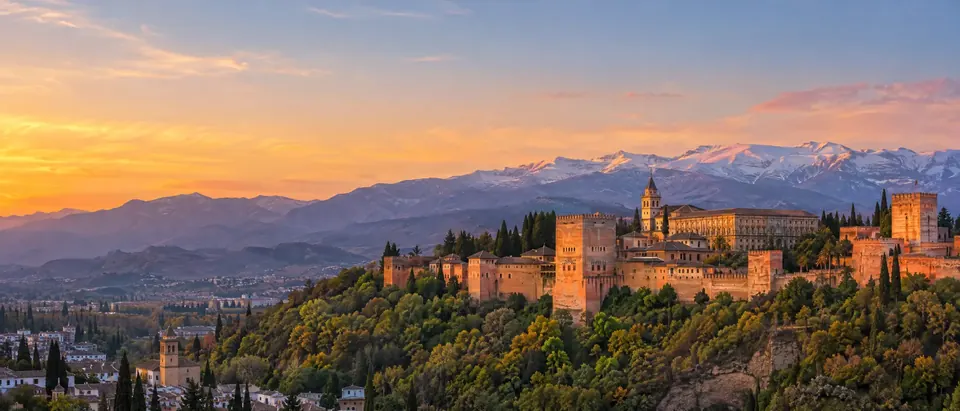
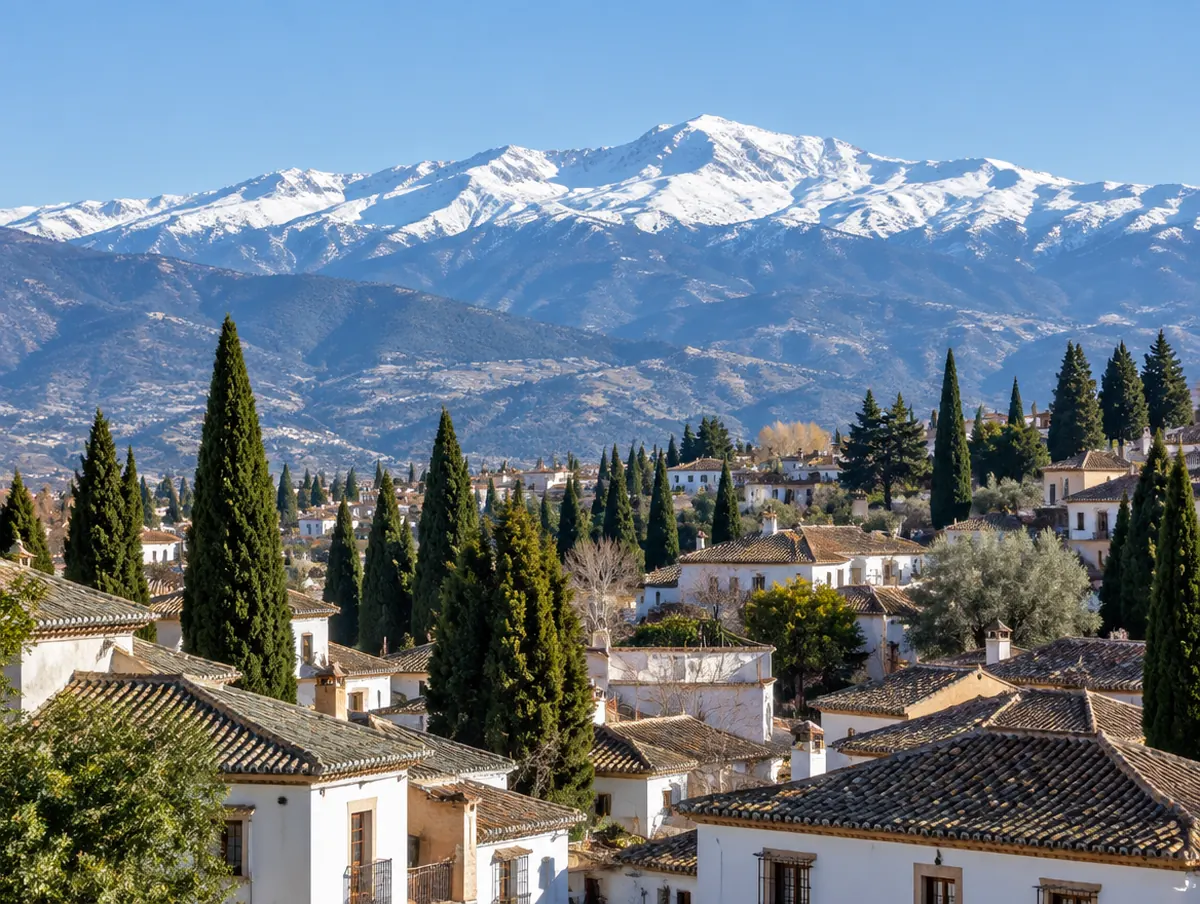
The Alhambra and the Sierra Nevada, Granada
AI-generated image
Visit the full Hipoteken website
Euribor 12M
This month, avg
3.216%
October 2026, 1–14 Oct average
Official monthly
3.247%
September 2026

Updated 15 October 2026

Granada

Buying here?
We handle the mortgage.

Granada mortgages for international buyers

We arrange mortgages across Granada province — Almunecar, La Herradura, Salobrena, Motril and the Costa Tropical, Granada city, Monachil and the Alpujarras — for buyers from the UK, Ireland, the Netherlands, Germany, Scandinavia, the USA and beyond. Every step is handled remotely, so you never need to fly out to sign a form.

  • Over 320 days of sunshine on the Costa Tropical
  • We put banks in competition for you
  • Increase your chances of a mortgage!
  • Same day appointments available
  • Access preferential rates
  • Reduce the stress and let us work for you

Instant Simulation!

It takes 1 minute to learn how much you can borrow and monthly payment!

Please enter the property price.

Non-resident: you pay income tax outside Spain. Resident: you pay income tax in Spain.

Please enter an age between 18 and 74.
Excellent Read our reviews → 4.9/5 140 reviewson Trustpilot

Registered and regulated by the Bank of Spain. Registration number D647 — HIPOTEKEN, S.L. See more here

Four separate markets in one province

Granada runs from the Sierra Nevada down to the Costa Tropical, and a bank reads each part of it differently. City flats are the most straightforward lending in the province. The coast is steady. The Alpujarras and the northern altiplano are thin markets where the list of willing lenders is short and knowing it is the whole job.

Maximum advance and term depend on your residency, age and income, and vary between lenders. We confirm the exact figures for your purchase before you commit to anything.

AI-generated image: a historic Andalusian city of tiled rooftops and cypress trees with a high snow-capped sierra rising behind it, clear winter light, no people AI-generated

From ski slopes to subtropical coast

Granada runs from the Sierra Nevada down to the Costa Tropical, so you can ski in the morning and reach the sea by afternoon. The coast gets over 320 days of sunshine and sits within about an hour of three airports. Prices come in under Málaga but above the inland provinces, and the province contains four or five genuinely separate markets.

AI-generated image: the horseshoe bay of la herradura seen from the cliff road at golden hour, wooded headlands either side, calm water, no peopleAI-generated

The most liquid coast

Almuñécar and La Herradura

The busiest market on the Costa Tropical and its easiest to finance. Cliffs, coves, avocado and mango terraces behind, and a town that stays open through the winter rather than shuttering in October. Enough sales happen here each year for lenders to know the area, value it confidently and move at a reasonable pace — which is not true of everywhere else in this province.

AlmunecarLa HerraduraItrabo
AI-generated image: salobreña's white houses and castle on their rock above green cane fields and the sea, warm late light, no peopleAI-generated

Everyday Costa Tropical

Salobreña and Motril

Motril is a working port and the coast's commercial centre; Salobreña is the white village stacked on its rock above the beach. Together they are the ordinary end of the Costa Tropical — year-round residents, steady resale volume and apartment stock a valuer can price from a dozen recent sales rather than two. Entry prices sit below Almuñécar for something broadly comparable.

SalobrenaMotrilMolvizarLobres
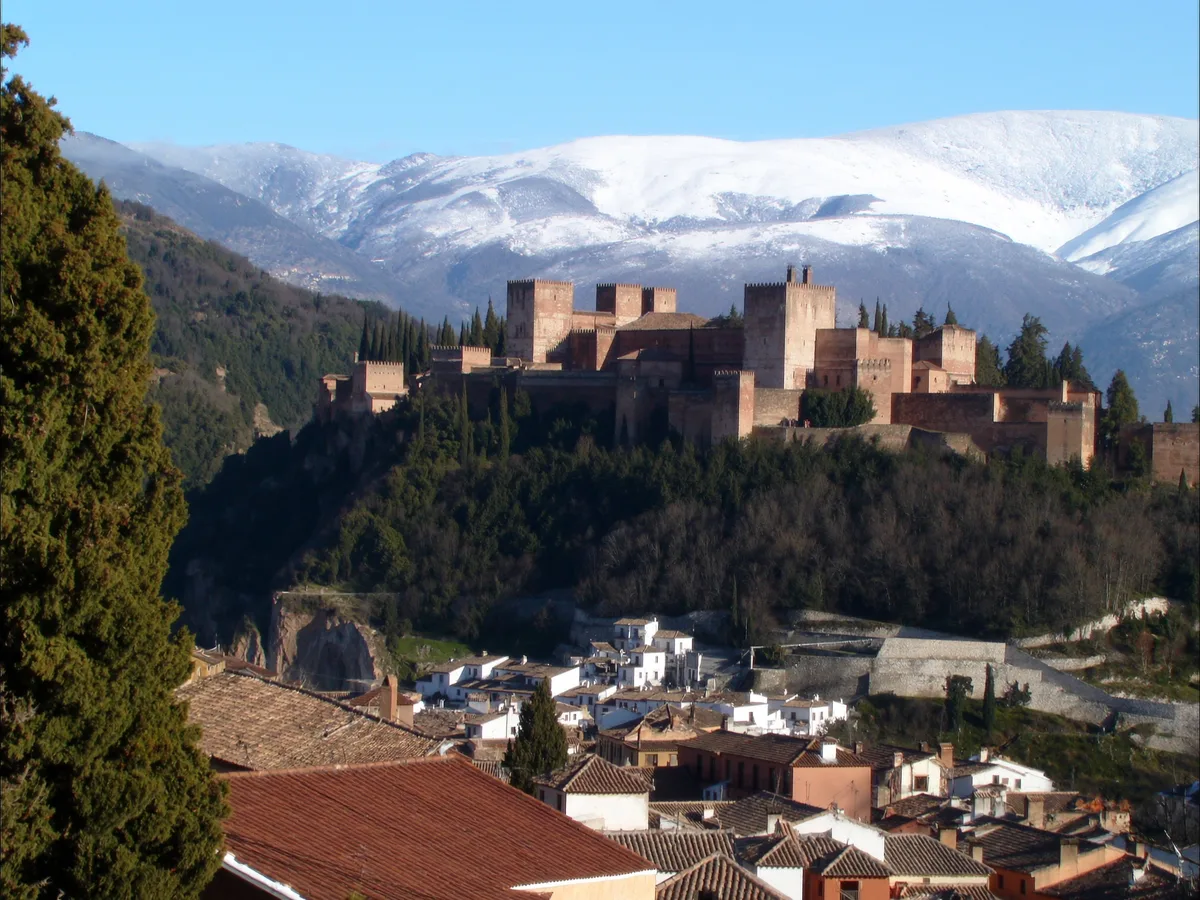
AI-generated image: the alhambra and the snow line of the sierra nevada behind it, seen across granada's tiled rooftops in clear winter light, no peopleAI-generated

The safest lending in Granada

Granada city and Monachil

A dense historic centre, a large university population, free tapas and rental demand that renews itself every September. Banks are comfortable here in a way they rarely are on a coast: urban flats, plentiful comparables, quick valuations, familiar rental logic. Monachil puts the Sierra Nevada road on the doorstep, and the western towns of Loja and Montefrío pull the price level down again.

Granada cityMonachilLojaMontefrio
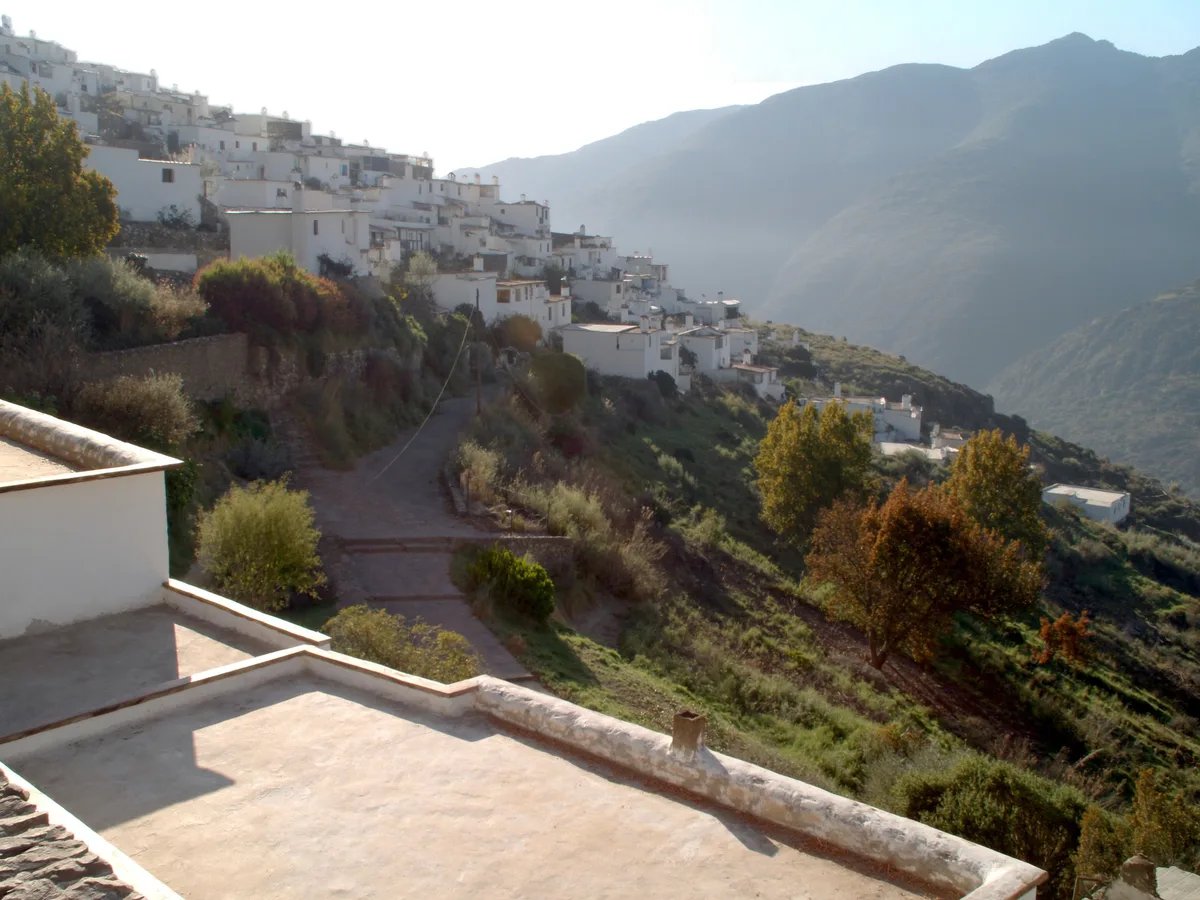
AI-generated image: flat-roofed white alpujarran houses stepped down a steep terraced slope with chestnut trees and high sierra above, soft morning light, no peopleAI-generated

Thin market, real character

The Alpujarras: Órgiva and Lanjarón

Whitewashed and tiered on near-vertical terrain, with a small and determined group of buyers. Access, terraces, water rights and rustic land all complicate a valuation, and the list of banks willing to lend on a restored village house up here is short. Perfectly financeable with the right lender approached in the right way — which is exactly where a broker earns their keep.

OrgivaLanjaronVelez De Benaudalla
AI-generated image: a small grey-sand cove backed by steep dry headlands and a handful of low white houses near castell de ferro, clear light, no peopleAI-generated

The quiet eastern strip

Castell de Ferro, Calahonda and Carchuna

A run of small beach villages east of Motril, cheaper than the resorts on either side. Modest stock and slow turnover mean a valuation rests on very few comparables, so the figure the bank comes back with is worth testing early rather than late.

Castell De FerroCalahondaCarchunaTorrenueva
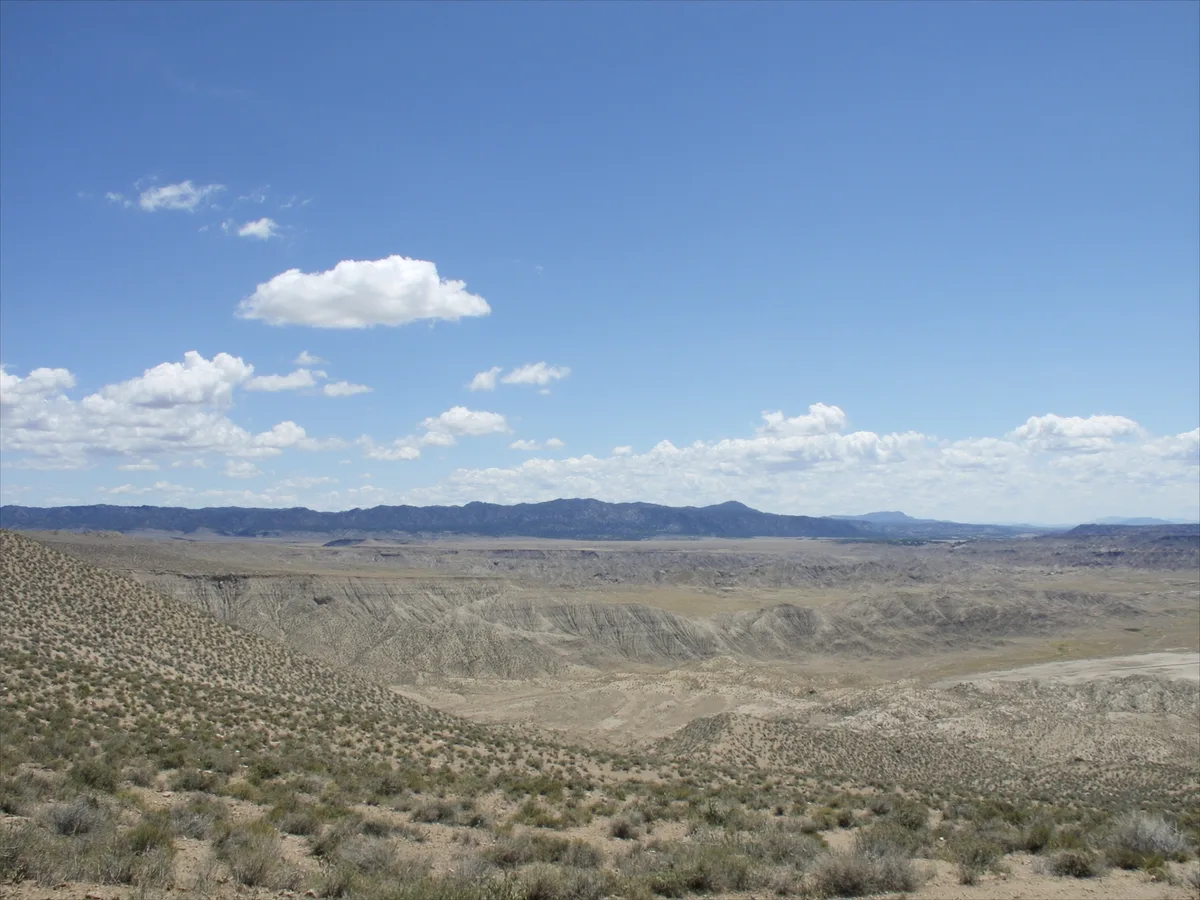
AI-generated image: eroded pale badlands and a wide empty plateau near galera under a huge sky, distant sierra on the horizon, no peopleAI-generated

High, dry and cheap

The northern altiplano: Baza, Galera, Huéscar

Big skies and bare plateau in the far north of the province, closer to Murcia than to the sea. Values bear no relation to the coast and much of the market moves in cash, so financing here is largely a question of which lenders look this far inland at all.

BazaGaleraHuescarCullarBenamaurelCanilesFreila
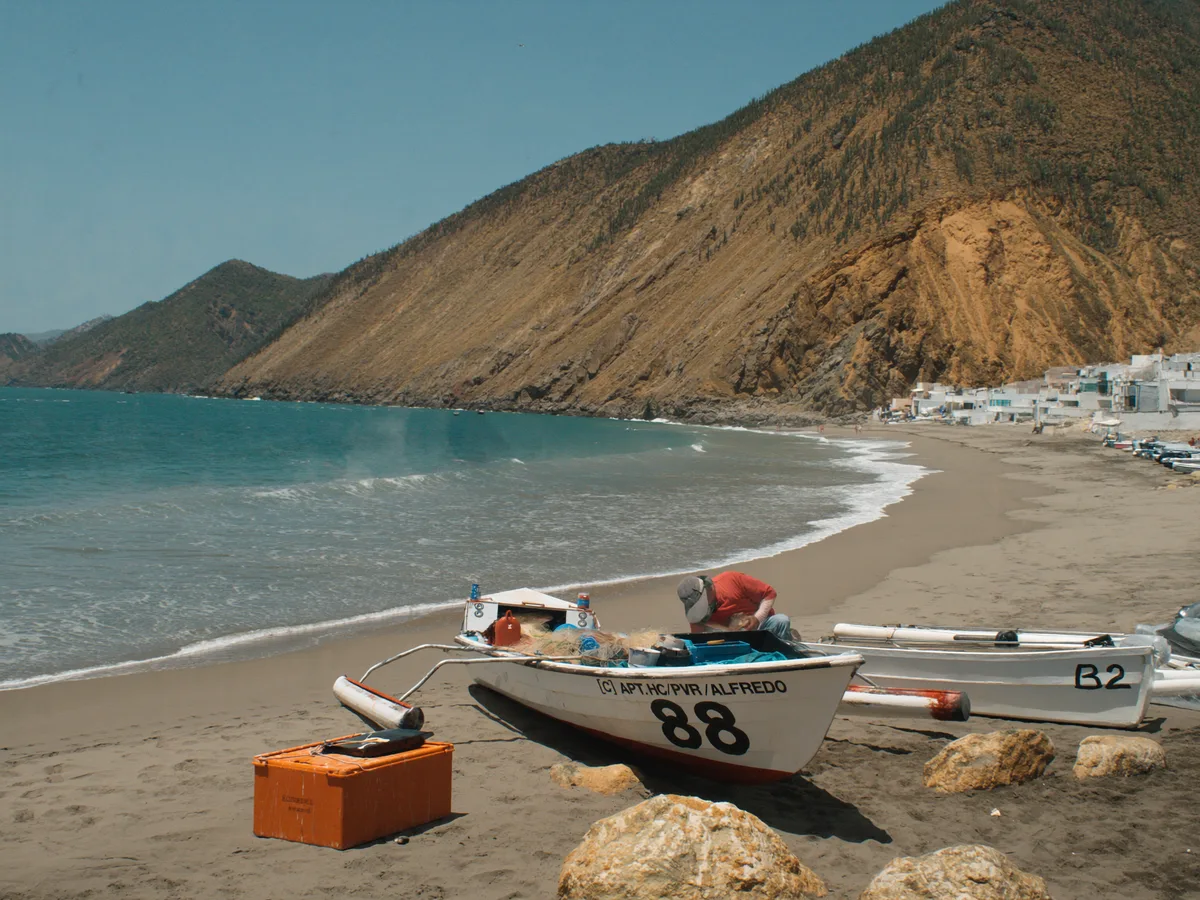
AI-generated image: a narrow coastal village of white houses pressed between a steep brown mountainside and a grey pebble shore near la rábita, hazy afternoon light, no peopleAI-generated

Last coast before Almería

Gualchos, La Rábita and Albuñol

Subtropical growing country and small working villages on the final stretch of Granada coastline. Very little international stock changes hands, so comparables are thin and a lender unfamiliar with the area tends to price that uncertainty into its valuation.

GualchosLa RabitaAlbunol

Buying somewhere not on this list?

A rural finca, a plot for a self-build, a village nobody mentions in the brochures — we arrange mortgages right across the archipelago. Send us the address and we will tell you which lenders will look at it, usually the same day.

Ask about your property

Let’s get started!

Six steps from first conversation to keys in hand. We handle the parts that are slow, confusing or in Spanish.

  1. Discovery

    Tell us about your situation — property price, area of interest, your tax residency and your income. The best way to do this is to schedule a call or send us your details. You will come out of this call with a full understanding of the possibilities and of the process ahead.

  2. Simulation & start!

    As a follow-up to the call you receive a detailed simulation of your potential mortgage — savings needed, monthly repayment, costs. We also set out exactly which documents are needed to get going.

  3. Let’s document!

    This is the part where we need you. The more complete your file, the better your chances of a fast and competitive mortgage offer.

  4. Application & Negotiation

    We work through your documents and apply to get banks competing for your mortgage, fighting on your behalf for the best rates and terms.

  5. Valuation of the property

    An official appraisal is coordinated between your estate agent or vendor and a licensed valuation company.

  6. Completion

    Once everything is tied up, our specialised completions team supports you all the way. We coordinate with your estate agent, solicitors, bank and notary to push the process through smoothly.

Meet the team

Our team is based in Valencia, Spain, working with mortgages all around Spain.

Raj Kumar Sirwani, CEO and Founder at Hipoteken
Raj Kumar Sirwani
CEO & Founder
SpanishEnglish
Philip Lee, Director at Hipoteken
Philip Lee
Director
SpanishEnglish
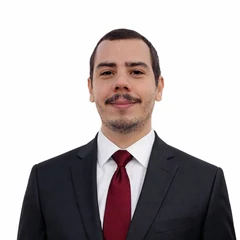
Daniel Morante, Mortgage Adviser at Hipoteken
Daniel Morante
Mortgage Adviser
SpanishEnglish
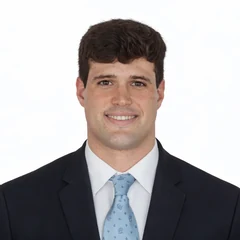
Alberto García, Mortgage Adviser at Hipoteken
Alberto García
Mortgage Adviser
SpanishEnglishGerman
Alejandro Madrigal, Mortgage Adviser at Hipoteken
Alejandro Madrigal
Mortgage Adviser
SpanishEnglish
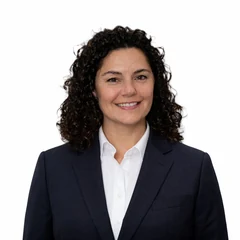
Nuria Garca, Mortgage Adviser at Hipoteken
Nuria García
Mortgage Adviser
SpanishEnglish
Louisa Koole, Mortgage Adviser at Hipoteken
Louisa Koole
Mortgage Adviser
SpanishEnglishDutch
Luis Boris Grateron, Completion Coordinator at Hipoteken
Luis Boris Grateron
Completion Coordinator
SpanishEnglishGerman
Daniel Santiago, Business Development at Hipoteken
Daniel Santiago
Business Development
SpanishEnglish
Maria Jos Valero, Completion Coordinator at Hipoteken
Maria José Valero
Completion Coordinator
SpanishEnglish

Meet the whole team on hipoteken.com →

This is where we focus and specialize

Most of our Granada clients live outside Spain and are buying here for the first time. Some already live in Spain. We handle both.

Non-resident buyers

You live and pay tax outside Spain. Expect to borrow up to around 70% of the property price and fund the rest plus costs yourself. This is our largest group by far.

Spanish residents

You live and pay tax in Spain. Loan-to-value typically rises to 80%, and a wider set of lenders opens up to you.

Investment purchases

Buy-to-let and second homes. Lenders assess these differently, and the right bank matters more than the headline rate.

Remortgaging in Spain

Already have a Spanish mortgage on a worse rate? Moving lender is often straightforward and the saving over a full term can be substantial.

Construction & renovation

Building or substantially renovating needs a different product and a lender comfortable with staged drawdown.

Complex income

Self-employed, company director, multi-currency or several income sources. This is where a broker earns their keep.

★★★★★
Raj was efficient and professional from start to finish, from quickly finding the best offer through to the closing process.
Google review Jonathan & VictoriaUnited Kingdom
★★★★★
We approached other brokers and banks directly and could not get the offer we wanted. Raj and the team secured us the best deal.
Google review DanielUnited Kingdom
★★★★★
Our situation was a bit tricky and Raj managed all the questions from the bank with ease. He secured us a great deal.
Google review MelissaUnited States
★★★★★
I had a more difficult application as a self-employed person. With unbridled energy he applied to various banks and got it.
Google review KarinNetherlands
★★★★★
Not being aware of the way of banking in Spain, we can fully recommend Hipoteken. Good and fast communication.
Google review ArminGermany
★★★★★
Hipoteken have been a God send, not least because I am self employed in the UK and had difficulty proving my income.
Google review SamUnited Kingdom
★★★★★
Simply without Hipoteken I could not have purchased my new property. They supported me throughout the entire process.
Google review AlessandroItaly

Reviews published on Trustpilot and Google.

Book a call with a mortgage adviser

Pick a time that suits you. Twenty-five minutes, by phone or Google Meet, with an adviser who works on international cases every day. No cost and no obligation.

Initial mortgage consultation 25 minutes · by phone or Google Meet · English, Spanish, German or Dutch
Free

Not loading? Open the booking page in a new tab Prefer to write instead? Send us your details and we will come back to you.

Frequently asked questions

The questions buyers ask us most often about mortgages in Granada, answered directly.

Can I get a mortgage in Granada as a non-resident, or if I have just moved to Spain?

Yes — clearly. Spanish banks lend both to non-residents and to international clients who have only recently moved to Spain, as long as you meet their lending requirements.

What are the key factors Spanish banks look at to approve a mortgage?

Criteria vary from bank to bank, and even within the same bank depending on the route your application takes to reach them. The key factors are:

  • Debt-to-income ratio (DTI) — the central ratio a bank uses to assess a mortgage. Each bank has its own criteria and its own way of calculating it, but as a general rule they will lend where DTI stays below 35%.
  • Stability of income — how long you have been in your current job, or running your current business, matters a great deal.
  • Saving capacity — banks want to see clients who save and who run their finances in an organised way. Having the funds available to cover the share the bank does not lend is essential.
  • Credit history — they pay less attention to the score itself than to your record of past borrowing, and to any defaults or late payments.
How much can I borrow for a property in Granada?

Spanish banks set a maximum loan-to-value (LTV) based on the currency you are paid in and on your tax residency.

As a general rule, non-resident mortgages are limited to 70%, while residents in Spain can generally borrow up to 80%. Some exceptions apply, and across the market the full range runs from 50% to 75% for non-residents.

That is the maximum, though. Your finances still have to show the bank what it wants to see on DTI, on savings and on the rest.

How much deposit do I need to buy in Granada?

On a non-resident mortgage where the bank covers 70%, you would need to cover the remaining 30%, plus the costs of buying. Those costs vary considerably depending on the region of purchase, and can range from 8% to 15%.

What are the costs of buying a property in Granada?

Beyond the property price itself, you need to budget for the following:

  • Taxes
    • Resale: between 6% and 11%, depending on the region of purchase and the price of the property.
    • New build: 10% VAT, plus stamp duty — which again varies by region, between 0.5% and 1.5%.
  • Legal costs — we recommend appointing a lawyer to carry out the legal checks and to guide you through the whole purchase process. Allow around 1%, although the percentage will be higher on lower-value properties.
  • Notary and land registry costs — allow up to 1%.
And what are the costs of obtaining a mortgage in Spain?

By law, Spanish banks cover all of the set-up costs of a mortgage. That leaves the borrower with two: the valuation of the property — between €500 and €2,500, depending on its value — and the broker's fee.

Our fee depends on the mortgage amount. Once we have spoken and understood your situation, we prepare a personal simulation for you, and the fee is set out in full there — so you see it alongside the mortgage figures, before you commit to anything. It is purely success-based: nothing is payable until the purchase completes.

How long does it take to get a mortgage in Granada?

Once we have collected all of your financial documents, we apply to the banks for approval. That can take anywhere from 48 hours in straightforward cases to a few weeks in more complex ones.

Bear in mind, too, that banks slow down substantially over holiday periods — summer, Easter, Christmas and local holidays.

Once your mortgage is approved, carrying out the property valuation and getting everything ready to sign takes a further four to six weeks.

How do mortgage rates work in Spain?

Unlike many countries, Spain offers fixed rates that run for the entire life of the mortgage. So when you sign, you can fix your interest rate for the whole term.

The types of mortgage available are:

  • Fixed rate — one interest rate for the whole term.
  • Variable rate — generally indexed to 12-month Euribor. The rate is recalculated every 6 or 12 months, and is the index rate plus an agreed spread.
  • Mixed rate — a combination of the two. The rate is fixed for typically 5 to 10 years, after which the mortgage becomes variable: indexed, and revised every 6 or 12 months.

Rates move a great deal with central bank rates and with Euribor, so the best way to find out where they stand today is to speak to us.

Do I need an NIE to get a mortgage in Granada?

Yes, you will need an NIE number eventually — but we can start the process without one, and we will guide you through the easiest way to obtain it later on.

Can the mortgage process be done online?

Yes. With us, the entire process is handled online, with no need to travel or to visit banks until the last stages. We work with banks that are able to run the process fully online.

Signing the purchase and the mortgage at the notary is the only step that requires travelling — and even then, it is very common to give power of attorney to your lawyer so that they can sign the deeds on your behalf.

Why use a mortgage broker rather than going straight to the banks?

Experience in mortgages allows a broker to present your application in the best possible way, to the right banks, and then to push those banks for approval and for the best terms available.

With mortgage terms typically running 15 to 25 years, a small reduction in the interest rate obtained can mean thousands of euros saved over the life of the loan.

And that is before the hassle of shopping around bank after bank yourself — waiting on answers that never arrive, or getting a flat no simply because something in your file was not understood.

We do the hard work of understanding your case, presenting it to the banks most likely to say yes, and fighting for the best possible terms for you.

Free & no obligation initial consultation Fees only on success

Contact us

Send us your details, along with anything specific you would like us to know, and we will be in touch shortly. Remember:

  • No obligation and no cost to enquire
  • A real adviser, not an automated quote
  • We work in English, Spanish, German and Dutch
  • Your details are never sold or shared

Your details (obligatory fields)

Please enter your first name.
Please enter your last name.
Please enter a valid email address.
Please enter your phone number.
Please accept the privacy policy to continue.

Hipoteken is an independent mortgage intermediary. This is an enquiry, not a mortgage application, and places you under no obligation.

Ready to find out what you can borrow? No obligation, no cost, and no fee until your mortgage is approved.

Contact us WhatsApp